Market overview of the Artificial Intelligence (AI) In Procurement Market
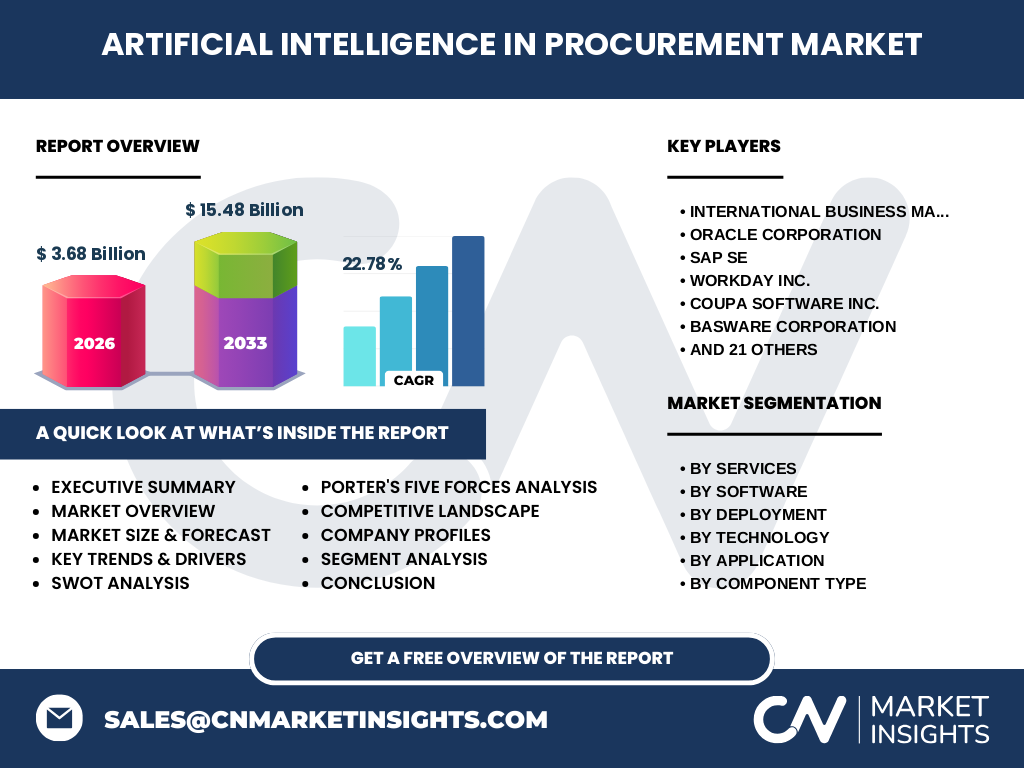
Our analysis indicates that the Artificial Intelligence (AI) In Procurement Market represents a fundamental transformation in enterprise operations, scaling from 3.68 Billion in 2026. This sector encompasses advanced software and specialized services designed to automate sourcing, mitigate supply chain volatility, and optimize indirect spend across global manufacturing and retail hubs.
Key market drivers, restraints, challenges, and opportunities shaping Artificial Intelligence (AI) In Procurement Market
The Artificial Intelligence (AI) In Procurement Market industry trends are propelled by escalating supply chain disruptions and complex trade compliance mandates. While legacy system integration bottlenecks act as short-term restraints, unprecedented opportunities exist in deploying predictive analytics for raw material sourcing and tier-3 supplier risk visibility.
Structural Growth Drivers and Emerging Patterns
The rapid expansion of the Artificial Intelligence (AI) In Procurement Market is heavily driven by the necessity for real-time spend visibility and automated contract compliance. Enterprises increasingly rely on machine learning algorithms to neutralize inflationary pressures and secure resilient supplier networks across volatile commodity markets.
COVID-19 Impact Analysis and Market Recovery
Pandemic-induced supply shocks exposed severe vulnerabilities in traditional procurement workflows, permanently altering the trajectory of the Artificial Intelligence (AI) In Procurement Market. Enterprises accelerated digital transformation initiatives, shifting capital from manual vendor management toward autonomous procurement platforms capable of dynamic scenario planning during global logistics crises.
Competitive Benchmarking and Strategic Dynamics
Market concentration within the Artificial Intelligence (AI) In Procurement Market analysis is characterized by a mix of legacy enterprise resource planning giants and agile pure-play innovators. Industry leaders continuously leverage strategic acquisitions and native AI integrations to capture high-margin enterprise accounts across manufacturing and public sectors.
Executive Summary of Key Findings
Our comprehensive evaluation highlights a projected expansion to 15.48 Billion by 2033, driven by a robust CAGR of 22.78%. Organizations failing to adopt cognitive sourcing solutions risk severe margin erosion amidst escalating raw material costs and tightening regulatory compliance standards across international trade corridors.
Market Forecast and Revenue Trajectory
The Artificial Intelligence (AI) In Procurement Market market size is set for explosive acceleration, expanding from 3.68 Billion in 2026 to 15.48 Billion by 2033 at a CAGR of 22.78%. This trajectory reflects widespread enterprise migration toward automated spend analytics and cognitive supplier management tools.
Segmentation Analysis Across Solutions and Services
The Artificial Intelligence (AI) In Procurement Market is segmented by Services (Consulting, Implementation, Integration, Support, Managed Services), Software (Spend Analysis, Supplier Management, Contract Management, Procurement Automation, Sourcing), Deployment (Cloud-Based, On-Premises), Technology (Machine Learning, NLP, Computer Vision), Application, Component, and Industry Vertical.
Regional Market Analysis and Geographic Distribution
Geographic performance in the Artificial Intelligence (AI) In Procurement Market varies based on regional manufacturing density, regulatory maturity, and cloud infrastructure adoption. North America currently commands the highest market share, supported by early enterprise AI integration, while Asia-Pacific exhibits the fastest-growing adoption rate.
In-Depth Regional Review of Growth Hotspots
North America leads the Artificial Intelligence (AI) In Procurement Market due to high concentrations of technology innovators and stringent corporate governance standards. Meanwhile, Europe is rapidly expanding, propelled by strict regulatory frameworks like the EU Supply Chain Act, compelling enterprises to adopt advanced risk management software.
Company Profiles and Strategic Positioning
Major ecosystem participants include International Business Machines Corporation, Oracle Corporation, SAP SE, Workday Inc., Coupa Software Inc., Basware Corporation, GEP Worldwide LLC, JAGGAER LLC, Ivalua Inc., and specialized innovators like Zip, Zycus Inc., Prewave, Omnea, Scoutbee GmbH, and Sievo Oy, each driving distinct automation paradigms.
Porter's Five Forces Analysis of Competitive Pressures
In the Artificial Intelligence (AI) In Procurement Market, supplier power is moderate due to specialized proprietary algorithms, while buyer power remains high as enterprises demand seamless ERP interoperability. Threat of substitution is low, but competitive rivalry is intense among tech giants and agile startups.
SWOT Analysis of the Industry Ecosystem
Strengths include high predictive accuracy and operational cost savings. Weaknesses involve data privacy concerns and complex integration hurdles. Opportunities lie in emerging generative AI applications for contract negotiations, while threats stem from potential cybersecurity vulnerabilities and evolving cross-border data protection regulations.
Value Chain Analysis from Raw Materials to End-Users
The value chain spans raw material data aggregation, machine learning model training, software development, implementation services, and ultimate deployment by enterprise end-users in retail, healthcare, and manufacturing. Value creation heavily concentrates in proprietary AI software layers that automate complex transactional workflows.
Investment Insights and High-Potential Opportunities
Investors in the Artificial Intelligence (AI) In Procurement Market should prioritize scale-ups specializing in autonomous contract management, predictive supplier risk analytics, and niche vertical solutions for heavily regulated industries like government and healthcare to capture outsized returns.
Conclusion and Strategic Takeaways
The data confirms that the Artificial Intelligence (AI) In Procurement Market is transitioning from an emerging technology to a mandatory operational imperative. Achieving a 22.78% CAGR through 2033 proves that cognitive procurement tools are central to long-term corporate resilience and cost leadership.
Research Methodology and Baseline Triangulation
Our research methodology triangulates bottom-up market sizing from trade registries and financial disclosures with extensive primary interviews involving chief procurement officers, technology architects, and macroeconomic analysts to ensure absolute data integrity across all forecast metrics.
Scope of the Report and Analytical Parameters
This report evaluates the global Artificial Intelligence (AI) In Procurement Market across all specified software, deployment, technology, and regional segments from 2026 to 2033. Macroeconomic headwinds, geopolitical trade policies, and enterprise IT budgets serve as core bounding parameters for our analytical models.
Recent Developments, Partnerships, and Strategic Moves
Recent market momentum is defined by strategic mergers, generative AI product rollouts, and cross-border vendor partnerships among market leaders like Coupa, SAP, Jaggaer, and specialized innovators like Arkestro and LevaData, aiming to deliver end-to-end autonomous source-to-pay capabilities.